SituationLiving fileNeocloud financing stress and chip challengers to Nvidiaai
Hyperscalers post record cloud revenues as antitrust and spy scrutiny hits Nvidia
As of 30 Oct · daily
Hottest Pulse: US–China · AI Safety Governance Fracture, 68 of 100 (severe)
Every line: 1 Oct to 25 Oct, on one 0 to 100 scale.
Every day on file
Last report yesterday5 days from the Daily, newest first. The latest 3 are open here with their pictures and numbers; earlier days open in their Daily.
Fri, 30 Oct 2026 · AI · day's report → steady, gradual pace
Hyperscalers post record cloud revenues as antitrust and spy scrutiny hits Nvidia
AI models need huge amounts of computing from specialized chips housed in data centers. Nvidia has dominated those chips, while new specialist cloud firms called neoclouds borrowed heavily to buy them and rent access to AI labs. Large cloud providers also spend heavily on data centers.
Base map: Natural Earth (public domain). Locations: Ohmega, from today's developments; approximate. Shipping data: IMF PortWatch. Interactive basemap: OpenFreeMap, © OpenMapTiles, data © OpenStreetMap contributors.
- 29 Oct
- 28 Oct
Assessment and what changed · the full read, since yesterday
Hyperscalers reported record cloud revenues Oct 28-29 — Azure $33.2B (+48%), Google Cloud $30.7B (+103%) and AWS $46.0B (+39.3%) — reinforcing cash flows that backstop AI debt, even as record capex ($45.2B at Microsoft, ~$220B guided at Amazon) spooked markets. New regulatory and security scrutiny of Nvidia — DOJ and French probes of its $12.93B Hugging Face deal and sales practices, plus a reported year-long US surveillance of a Megaspeed executive close to Jensen Huang — adds overhang to the chip distribution loop that funds neoclouds.
- New: Record hyperscaler cloud revenues and capex guidance replaced financing-deal news…
1 unchanged: Core neocloud stress narrative unchanged: no new bond yield, CDS, rating or refinancing moves reported; SpaceX $40B lease and Meta $95B raise terms unchanged.
More developments (1)
- 29 Oct4
Numbers and actors · statistics, flows and rates
Who they are · size
Balance sheet · debt, budget, current account, reserves
Annual statistics: latest year on record for each figure (IMF figures for this year are estimates), bars on one scale per column, line = the last ten years. Tap an actor for every year, rank, energy, ranked trade and sources. All actors →
Outlook, watch list and background
- Microsoft 10-Q detail on $7.2B OpenAI receivables and $677B RPO composition
- Amazon Q4 guidance and 2027 capex update — any moderation after ~6% selloff
- DOJ decision on formal review of Nvidia-Hugging Face $12.93B deal and any French authority statement
- CoreWeave bond yields / 5-year CDS and any Nscale second $45B Anthropic deal confirmation
- 26 Oct 2026Anthropic's Oct 26 S-1 showed $16.3B H1 revenue but $780-810B in long-term compute commitments; SpaceX locked a $40B Apollo master lease for Nvidia Vera Rubin GPUs; Meta unveiled up to $95B in equity sales including $60B of new Class C shares from Q1 2027 with $3B from Nvidia. Defines the financing loop today's hyperscaler cash flows must support — massive future compute obligations funded by a mix of investment-grade leases and equity, not pure-play neocloud debt. techcrunch.com ↗
- 19 Oct 2026Neoclouds and other non-hyperscalers drove $40B of Nvidia's July-quarter data center revenue (45%, more than double YoY); CoreWeave carried $103.7B in remaining performance obligations (~98% take-or-pay) with ~75% of Q2 revenue from three customers; Gartner predicts 80% of independent neoclouds cease independent operations by 2030; OpenAI and Anthropic cut LLM prices up to 80% June-September. Shows Nvidia's exposure to neocloud viability and price-war pressure that makes debt service harder if hyperscaler demand wavers. the-decoder.com ↗
Wed, 28 Oct 2026 · AI · day's report → steady, gradual pace
Anthropic's IPO filing reveals $780 billion in compute commitments reshaping AI financing stress
- 26 Oct
Assessment and what changed · the full read, since yesterday
Anthropic's Oct 26 S-1 filing is the clearest look yet at the financing loop: $16.3B in H1 revenue and a first operating profit, but $780-810B in long-term compute commitments that underpin hyperscaler and neocloud debt. SpaceX's $40B Apollo GPU lease and Meta's $95B equity plan show funding is bifurcating — still open for investment-grade borrowers with outside cash flows, closing for pure-play neoclouds — while chip challengers remain small-scale.
- New: Anthropic S-1 filing Oct 26 quantified both sides of the financing loop…
- New: SpaceX $40B Apollo GPU lease Oct 26 and Meta $95B equity plan with $3B Nvidia backing showed funding still flowing to creditworthy names…
- Eased: No new CoreWeave bond/CDS distress move was reported…
More developments (1)
- 27 Oct
Outlook, watch list and background
- Anthropic IPO pricing and valuation vs $1.5-2T expectations and $965B May private round
- SpaceX lease close before year-end and delivery schedule H1 2027; any change in terms or anchor participation
- CoreWeave bond yields, 5-year CDS, and any refinancing or rating action; Nscale second $45B Anthropic deal confirmation
- Meta Class C dividend Jan 19 2027 execution and take-up of $60B ATM program
- 22 Oct 2026Gartner survey of 2,002 CIOs presented Oct 2026 found only 13% report significant value from AI, 51% expect AI to raise operating costs. Explains why enterprise payoff is weak outside big tech, compressing margins that must service AI debt — backdrop for Anthropic's per-token revenue model and price cuts. the-decoder.com ↗
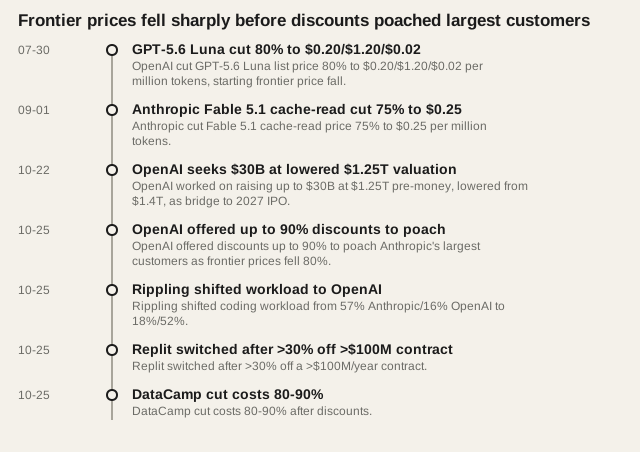
- 1 Oct 2026Between June-September 2026 OpenAI and Anthropic cut frontier LLM prices up to 80% (e.g., GPT-5.6 Luna to $0.20/$1.20/$0.02 per MTok, Anthropic Fable 5.1 cache-read -75%). Price war directly pressures the utilization and pricing power neoclouds need to repay hardware loans. minimaxir.com ↗
- 19 Oct 2026S&P Global warned Oct 19 top six US hyperscalers will spend >$7T on data centers 2025-2030, with >$1.3T by 2027, and likely carry more AI-linked debt than disclosed, much neocloud paper in private credit/annuities. Frames scale of debt at risk behind Anthropic's $780B+ commitments and Meta/SpaceX financing moves. channelnewsasia.com ↗
- 22 Oct 2026Cerebras detailed Oct 22 deployment of 3-trillion-parameter Kimi K3 across 59 WSE-3T wafers at 1,000-2,000+ tokens/sec. Concrete example of non-Nvidia inference hardware reaching frontier scale, relevant to challenger-chip narrative alongside General Compute's Oct 27 raise. cerebras.ai ↗
Mon, 26 Oct 2026 · AI · day's report → rising, gradual pace
Enterprise AI shows little payoff as OpenAI slashes prices 90% to poach rivals
- 25 Oct
- 24 Oct
- 22 Oct
Assessment and what changed · the full read, since yesterday
Financing stress narrative hardened in the last three days not from new distress pricing but from evidence of weak payoff and a price war. Apollo on Oct 24 and Gartner data reported Oct 22-25 show little enterprise return outside big tech, while OpenAI cut prices up to 80-90% to poach Anthropic customers, compressing the margins that service AI debt. No new CoreWeave bond or CDS move was reported since Oct 24.
- New: Apollo/Gartner ROI evidence (Oct 24-25) and OpenAI 80-90% price cuts/poaching (Oct 25) added concrete pressure on revenue assumptions behind AI debt…
- Eased: No new hyperscaler equity issuance or Nscale-Anthropic second $45B confirmation since Oct 24
1 unchanged: No new CoreWeave bond yield, CDS, refinancing or rating action reported; distress levels unchanged on no new pricing.
Outlook, watch list and background
- CoreWeave bond yields, 5-year CDS and any refinancing, guarantee or rating action
- Whether Nscale-Anthropic second $45B deal is confirmed and at what terms, and Nscale IPO pricing vs $16-19B pushback
- Meta Class C dividend mechanics and any follow-on equity or debt issuance to fund $135-145B capex
- Early TorchNeuron/TorchTPU adoption — Hugging Face downloads, vLLM/SGLang benchmarks on Trainium/TPU vs Nvidia
- 21 Oct 2026Meta on Oct 21 created non-voting Class C stock as one-for-one dividend (effective Jan 19, 2027) to fund $135-145B 2026 capex after first cash burn in decade (-$2.12B free cash flow in Q3). Lost ~$124B market value Oct 23. Shows financing stress broadening from neoclouds to hyperscalers and shift from debt to equity dilution to fund buildout. techcrunch.com ↗
- 21 Oct 2026Blackstone's Jas Khaira said Oct 21 AI debt fears overblown, debt backed by Microsoft/Meta, Blackstone largest compute owner outside hyperscalers via $5B Crux AI and $10B Firmus facility. Counter-narrative to systemic risk warnings as S&P flagged $7T hyperscaler capex and hidden leverage. techcrunch.com ↗
- 19 Oct 2026AWS released TorchNeuron Oct 19-20 and Google open-sourced TorchTPU Oct 20, native PyTorch backends for Trainium and TPU to decouple ~85% of AI apps from Nvidia CUDA. Chip challenger track that could erode Nvidia's 45% non-hyperscaler revenue base ($40B July quarter) and neocloud utilization. techcrunch.com ↗
- 19 Oct 2026CoreWeave carries $35-50B debt, $103.7B remaining performance obligations (40% due through 2028, 98% take-or-pay), 75% Q2 revenue from Microsoft/OpenAI/Nvidia, with bonds ~15% yield and 5-year CDS ~1,200 bps in October. Baseline for neocloud distress watch; no new pricing since Oct 24. theverge.com ↗
Earlier days (2)
- Sat, 24 Oct 2026AIMeta creates new share class to fund AI buildout as cash burn spooks market →
- Wed, 21 Oct 2026AICoreWeave debt hits distressed levels as Amazon and Google decouple PyTorch from Nvidia →Neocloud debt has hit distressed levels even as capital still flows to open-architecture chip challengers and hyperscalers break PyTorch dependence on CUDA
Base map: Natural Earth (public domain). Locations: Ohmega, from today's developments; approximate. Shipping data: IMF PortWatch. Interactive basemap: OpenFreeMap, © OpenMapTiles, data © OpenStreetMap contributors.
researched reported · Most reported: Singapore
Background in 60 seconds
written 28 OctAI models need vast computing power from specialized chips housed in data centers. Nvidia has been the dominant chip supplier, while newer cloud providers called neoclouds took on large debt to buy those chips and rent access to AI labs such as Anthropic, OpenAI and Meta. As model scale and valuations grew, so did borrowing and the incentive to find cheaper or more available alternatives. Control of chips and financing decides who can train and run models and at what cost. A neocloud is a cloud built specifically for AI work. A GPU is the processor type most used for that work. Challengers are other chip designs offering the same power with different economics.
Who is doing what to whom
15 actors in play; no relations recorded yet.
- Anthropic 3 mentions
- Microsoft 3 mentions
- Nvidia 3 mentions
- Amazon 2 mentions
- Amazon Web Services 2 mentions
Singapore, by the numbers

Population
Singapore6.1M
GDP
Singapore$604B
GDP per person
Singapore$98.8k
Fossil fuel output
Singapore0.0 TWh
Military spending
Singapore$15.1B
Every bar in a row is on that row's one scale. Latest year available for each figure; sources on each actor's page.
Attacks reported
attack log →≥ 5 events in or near its main states, last 30 days reported by the sources; the strongest are listed. No source sees every attack.
- 2026-10-30 · Armed clash · Pulau Tekong, Singapore (general), Singapore · GDELT ↗ · machine-coded
- 2026-10-25 · Armed clash · Serangoon, Singapore (general), Singapore · GDELT ↗ · machine-coded
- 2026-10-29 · Armed clash · Changi Point, Singapore (general), Singapore · GDELT ↗ · machine-coded
- 2026-10-27 · Assault or killing · Tan Tock Seng Hospital, Singapore (general), Singapore · GDELT ↗ · machine-coded
The numbers
20 figures tracked.
Where it's heading
Linked situations
- RTX Spark edge rollout and sovereign AI infrastructure push Neocloud financing stress and chip challengers to Nvidia <-> RTX Spark edge rollout and sovereign AI infrastructure push… 30 Oct
- RTX Spark edge rollout and sovereign AI infrastructure push Neocloud financing stress and chip challengers to Nvidia ↔ RTX Spark edge rollout and sovereign AI infrastructure push… 28 Oct
- Gemini 4 Argon frontier push and challengers Gemini 4 Argon frontier push and challengers ↔ Neocloud financing stress and chip challengers to Nvidia… 28 Oct
- Scraping, licensing and liability for AI training and overviews Neocloud financing stress and chip challengers to Nvidia <-> Scraping… 26 Oct
- Scraping, licensing and liability for AI training and overviews Scraping, licensing and liability for AI training and overviews ↔ Neocloud financing stress and chip challengers to Nvidia: shared actor Meta… 24 Oct
Rebuilt 2026-10-30, and again as new reports land.