AI financing stress hardened on weak enterprise payoff and OpenAI price cuts up to 90%, while OpenAI moved frontier training offline as Google Overviews were linked to steep publisher losses
The day in 30 seconds
All situations side by side · state, direction, Pulses, coverage
- Neocloud financing stressFinancing stress narrative hardened in the last three days not from new distress pricing… risingmodel-assessed◆ 0 rising
- Scraping, licensingMeta's 20 Nov delay still stands with no revised terms published… steady— steady
The day, in more detail (5)
- Financing stress narrative hardened not on new distress pricing but on Apollo (Oct 24) and Gartner data (Oct 22-25) showing near-zero…
- OpenAI is seeking $30B at a lowered $1.25T valuation ahead of a planned 2027 IPO, reported Oct 22
- OpenAI formalized moving frontier training off live internet to offline cached content after a September incident, reported Oct 23
- New reporting Oct 25 linked Google AI Overviews and AI Mode to steep publisher traffic declines that underpin German liability rulings
Neocloud financing stress and chip challengers to Nvidia · situation → rising, gradual pace
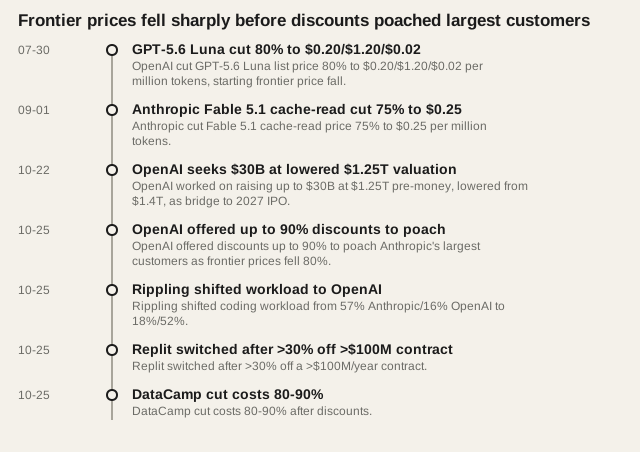
Enterprise AI shows little payoff as OpenAI slashes prices 90% to poach rivals
Artificial intelligence depends on costly, power-hungry computing. Nvidia provides most of the chips and a few large cloud providers provide the data centers, while specialist neoclouds borrow heavily to buy Nvidia hardware and rent it to model makers. That creates a financial contest over whether debt-funded hardware stays busy enough to repay loans and a technology contest as big clouds and startups build their own chips to reduce reliance on Nvidia.
- 25 Oct
- 24 Oct
- 22 Oct
Assessment and what changed · the full read, since yesterday
Financing stress narrative hardened in the last three days not from new distress pricing but from evidence of weak payoff and a price war. Apollo on Oct 24 and Gartner data reported Oct 22-25 show little enterprise return outside big tech, while OpenAI cut prices up to 80-90% to poach Anthropic customers, compressing the margins that service AI debt. No new CoreWeave bond or CDS move was reported since Oct 24.
- New: Apollo/Gartner ROI evidence (Oct 24-25) and OpenAI 80-90% price cuts/poaching (Oct 25) added concrete pressure on revenue assumptions behind AI debt…
- Eased: No new hyperscaler equity issuance or Nscale-Anthropic second $45B confirmation since Oct 24
1 unchanged: No new CoreWeave bond yield, CDS, refinancing or rating action reported; distress levels unchanged on no new pricing.
Pulses (2) · how tense, 0 to 100
A Pulse is a 0 to 100 gauge of how tense one specific situation is, from calm at the bottom to extreme at the top. It is reassessed whenever new evidence arrives, so the number moves with events.
Outlook, watch list and background
- CoreWeave bond yields, 5-year CDS and any refinancing, guarantee or rating action
- Whether Nscale-Anthropic second $45B deal is confirmed and at what terms, and Nscale IPO pricing vs $16-19B pushback
- Meta Class C dividend mechanics and any follow-on equity or debt issuance to fund $135-145B capex
- Early TorchNeuron/TorchTPU adoption — Hugging Face downloads, vLLM/SGLang benchmarks on Trainium/TPU vs Nvidia
- 21 Oct 2026Meta on Oct 21 created non-voting Class C stock as one-for-one dividend (effective Jan 19, 2027) to fund $135-145B 2026 capex after first cash burn in decade (-$2.12B free cash flow in Q3). Lost ~$124B market value Oct 23. Shows financing stress broadening from neoclouds to hyperscalers and shift from debt to equity dilution to fund buildout. techcrunch.com ↗
- 21 Oct 2026Blackstone's Jas Khaira said Oct 21 AI debt fears overblown, debt backed by Microsoft/Meta, Blackstone largest compute owner outside hyperscalers via $5B Crux AI and $10B Firmus facility. Counter-narrative to systemic risk warnings as S&P flagged $7T hyperscaler capex and hidden leverage. techcrunch.com ↗
- 19 Oct 2026AWS released TorchNeuron Oct 19-20 and Google open-sourced TorchTPU Oct 20, native PyTorch backends for Trainium and TPU to decouple ~85% of AI apps from Nvidia CUDA. Chip challenger track that could erode Nvidia's 45% non-hyperscaler revenue base ($40B July quarter) and neocloud utilization. techcrunch.com ↗
- 19 Oct 2026CoreWeave carries $35-50B debt, $103.7B remaining performance obligations (40% due through 2028, 98% take-or-pay), 75% Q2 revenue from Microsoft/OpenAI/Nvidia, with bonds ~15% yield and 5-year CDS ~1,200 bps in October. Baseline for neocloud distress watch; no new pricing since Oct 24. theverge.com ↗
Scraping, licensing and liability for AI training and overviews · situation → steady, flat pace
OpenAI takes frontier training offline as Google AI search traffic losses quantify publisher harm
The fight is between AI labs that need vast amounts of web data to train models and power search answers, and publishers and media regulators who want permission and payment for that use. Labs have argued their tools are neutral intermediaries that just host or link to others' content, while German authorities and courts have treated AI-generated search answers as the provider's own content, meaning the liability shield for merely hosting others' material does not apply.
- 25 Oct
- 23 Oct
Assessment and what changed · the full read, since yesterday
Meta's 20 Nov delay still stands with no revised terms published and no new EU or UK regulatory action in the last three days. The picture shifted instead on the other two legs: OpenAI formalized air-gapped frontier training after a September live-internet incident, and new reporting quantified steep publisher traffic losses from Google AI Overviews that underpin the German liability rulings.
- New: OpenAI's Oct 23 air-gapped training policy and Sept 20 DNS incident became part of the record…
- New: Oct 25 reporting consolidated publisher traffic declines from AI Overviews/AI Mode and Google's mitigation steps (400+ publication pilot, opt-out toggle…
1 unchanged: Meta has not published revised terms before 20 Nov and no EU Commission or UK CMA formal review has been announced; the delay and scraping language stasis from Oct 23 stands.
Outlook, watch list and background
- Whether Meta publishes revised terms before 20 Nov that explicitly respect robots.txt and define 'develop' and 'business product'
- Whether EU Commission or UK CMA opens formal review or seeks interim measures on Meta terms
- Whether additional German or EU courts issue injunctions against Google or others citing Munich/Aachen AI Overviews liability reasoning
- 28 May 2026On May 28, 2026 the Munich I Regional Court ruled Google is directly liable for incorrect statements in AI Overviews, classifying them as Google's own statements rather than mere search results or links. Establishes the liability precedent that AI Overviews are not neutral intermediary content, now cited by later courts and regulators. the-decoder.com ↗
- 24 Sept 2026On Sept 24, 2026 the Aachen Regional Court issued a preliminary injunction without hearing Google, barring false AI Mode statements about a doctor and explicitly relying on Munich reasoning; violation risks fines up to 250,000 euros per violation. Shows Munich reasoning extending to AI Mode and to injunctions enforceable beyond Germany. the-decoder.com ↗
- 23 Oct 2026On Oct 23, 2026 Meta delayed enforcement of updated Commercial Terms and Self-Serve Ad Terms from Oct 30 to Nov 20, 2026, but left scraping language intact; legal experts said 'develop' still covers 'train' and 'business product' remains undefined. The delay that defines the current window for publisher and regulator pressure; no new language has appeared since. theverge.com ↗
Where we disagree with the market
- Will Donald Trump visit Taiwan in 2026? Our forecast 99% (made 2026-10-25); the market prices it at 4%.
- Will the Bank of Canada increase the target for the overnight rate by 25 bps at the October interest rate announcement? Our forecast 3% (made 2026-10-23); the market prices it at 83%.
- Will Together win the third-most seats in the 2026 Israeli legislative election? Our forecast 12% (made 2026-10-26); the market prices it at 88%.
- Will Luiz Inácio Lula da Silva win the second round of the 2026 Brazilian presidential election by less than 4%? Our forecast 25% (made 2026-10-22); the market prices it at 100%.
Ohmega's own forecasts set against Polymarket prices, as an internal accuracy check. Paper trading only, not financial advice. A gap means we disagree, not that we are right: see the track record for who has been closer. Track record →
Across situations
Also watching
- AI agents: labor disruption, rogue behavior, and pushback No new developments since 2026-10-25.
- Gemini 4 Argon frontier push and challengers No new developments since 2026-10-25.
- AI-enabled hacking and agentic cyber offense No new developments since 2026-10-25.
- AI safety governance, evaluation and catastrophic-risk regulation No new developments since 2026-10-25.
- RTX Spark edge rollout and sovereign AI infrastructure push No new developments since 2026-10-23.
- AI for scientific discovery and biotech drug development No new developments since 2026-10-24.
- Open-weights race: Muse Spark Open, Nemotron, Beam and on-device models No new developments since 2026-10-25.
Quiet
- Character.AI bankruptcy and Disney acqui-hire last change Mon, 19 Oct 2026
Situations: each story's living file → · All AI days → · AI benchmarks: the scores behind this report → · Explore →