SituationLiving fileRTX Spark edge rollout and sovereign AI infrastructure pushai
Global AI compute doubling every nine months concentrates in US as water and noise backlash spreads
As of 30 Oct · daily
Hottest Pulse: Global Economy · Energy Price and Market Shock, 72 of 100 (severe)
Every line: 1 Oct to 24 Oct, on one 0 to 100 scale.
Every day on file
Last report yesterday4 days from the Daily, newest first. The latest 3 are open here with their pictures and numbers; earlier days open in their Daily.
Fri, 30 Oct 2026 · AI · day's report → steady, gradual pace
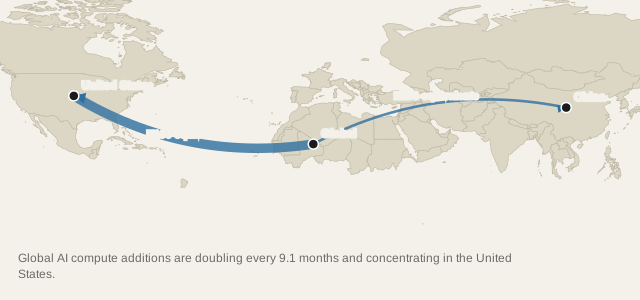
Global AI compute doubling every nine months concentrates in US as water and noise backlash spreads
Nvidia and partners are building AI that runs both on personal devices and inside national infrastructure. At the edge are RTX Spark PCs designed to run open-weight models locally, while at the other end are sovereign AI systems — data centers owned or controlled within a country so data and models stay under local rules — linked by plug-in data centers, Vera Rubin infrastructure and DSX PODs intended to cut deployment from months to days.
- 29 Oct
- 28 Oct
Assessment and what changed · the full read, since yesterday
Compute is still doubling every nine months and concentrating in the United States, now quantified at 78% of new additions in H1 2026, while local constraints broaden from power to water and noise. Nvidia advanced the edge stack with RTX Spark software and model updates on Oct 28, but Arizona water opposition and Mississippi buyouts show execution risk is rising at the site level. Confidence is high — all from Epoch AI, Nvidia blogs and The Verge reporting.
- New: Epoch AI quantified compute doubling every 9.1 months and U.S. concentration at 78% in H1 2026…
- Escalated: Local backlash broadened from power to water (Arizona 5M gal/day, 172 data centers…
1 unchanged: No new sovereign factory announcements or demonstrated DSX Flex/MaxLPS results at live sites; Texas audit, Florida ban and Kazakhstan milestones still pending as watch items.
More developments (1)
- 28 Oct
Numbers and actors · statistics, flows and rates
Who they are · size
Balance sheet · debt, budget, current account, reserves
Annual statistics: latest year on record for each figure (IMF figures for this year are estimates), bars on one scale per column, line = the last ten years. Tap an actor for every year, rank, energy, ranked trade and sources. All actors →
Outlook, watch list and background
- Texas audit outcomes and whether interconnection timelines lengthen for announced AI factories
- Florida legislative action on one-year hyperscale ban and Protecting Ratepayers Act
- Demonstrated DSX Flex/MaxLPS results at live sites and Minerva deployment reports
- Kazakhstan Data Center Valley construction milestones toward Q3 2027 and Ekibastuz Vera Rubin deployment
- 22 Oct 2026Nvidia said power is the biggest infrastructure bottleneck, with more than $300 billion in equipment backlogged and over 200 gigawatts waiting in U.S. interconnection queues, and positioned DSX Flex/MaxLPS for workload-aware power orchestration. Frames why compute doubling and U.S. concentration translate directly into grid and interconnection strain watched for DSX results. blogs.nvidia.com ↗
- 23 Oct 2026Firebird secured U.S. export license for 45,000 Nvidia Grace Blackwell GPUs for Kazakhstan Data Center Valley targeting Q3 2027 commercial launch, with Kazakhtelecom already deploying 400 H200 and 480 B300 GPUs in Astana and Almaty. Benchmark sovereign AI factory timeline against which U.S. water/power backlash and chip-import concentration are judged. blogs.nvidia.com ↗
- 16 Oct 2026RTX Spark laptops became available Oct 16, 2026 starting at $2,399 from ASUS, Dell, HP, Lenovo, Microsoft and MSI, with up to 128GB unified memory and up to 1 petaflop FP4 via Blackwell GPU + Grace CPU over NVLink-C2C. Hardware baseline for Oct 28 software/model updates that move edge rollout from availability to usability. blogs.nvidia.com ↗
Wed, 28 Oct 2026 · AI · day's report → steady, gradual pace
U.S. power and political backlash now constrain AI factory rollout despite sovereign buildout momentum
Base map: Natural Earth (public domain). Locations: Ohmega, from today's developments; approximate. Interactive basemap: OpenFreeMap, © OpenMapTiles, data © OpenStreetMap contributors.
- 27 Oct
- 26 Oct
Assessment and what changed · the full read, since yesterday
The sovereign and edge buildout did not advance with new factory announcements in the last three days; instead power and politics moved to the center. Anthropic's IPO filing and U.S. energy data underscored grid strain as the binding constraint, while the 2026 midterms turned data centers into a bipartisan target, raising execution risk for the DSX and Vera Rubin rollout. Confidence is high on the facts — all from company blogs and filings — but the direction now hinges on whether power-orchestration tools and efficiency bets can offset political and interconnection friction.
- Escalated: Political risk escalated from background to active constraint…
- New: Power bottleneck moved from Nvidia warning to issuer warning…
- New: Efficiency…
1 unchanged: Sovereign build milestones unchanged since Oct 23: no new Firebird/Kazakhtelecom construction updates or DSX POD delivery proofs reported.
More developments (1)
- 27 Oct4
Numbers and actors · statistics, flows and rates
Who they are · size
Balance sheet · debt, budget, current account, reserves
Annual statistics: latest year on record for each figure (IMF figures for this year are estimates), bars on one scale per column, line = the last ten years. Tap an actor for every year, rank, energy, ranked trade and sources. All actors →
Outlook, watch list and background
- Texas audit outcomes and whether interconnection timelines lengthen for announced AI factories
- Florida legislative action on one-year hyperscale ban and Protecting Ratepayers Act
- Demonstrated DSX Flex/MaxLPS results at live sites (Phaidra 10% claim, Emerald AI 100GW model) and Minerva deployment reports
- Kazakhstan Data Center Valley construction milestones toward Q3 2027 and Ekibastuz Vera Rubin deployment
- 21 Oct 2026On Oct 21, 2026, NVIDIA and Google Cloud announced general availability of Vera Rubin infrastructure via A5X instances on NVL72 systems, with expansion to Europe planned. Establishes the cloud-scale anchor for sovereign factories now facing power and political constraints. blogs.nvidia.com ↗
- 21 Oct 2026At GTC Berlin Oct 21, NVIDIA introduced DSX POD modular AI factories, integrated and validated before delivery to cut onsite deployment at a prepared site from six months to as little as 14 days. The 14-day claim is the delivery benchmark now being tested against grid and permitting delays. blogs.nvidia.com ↗
- 23 Oct 2026Kazakhstan's Firebird secured a U.S. export license for 45,000 Grace Blackwell GPUs, with Kazakhtelecom having deployed 400 H200 and 480 B300 GPUs in Astana and Almaty and planning 1,000+ GPUs in Data Center Valley and 1,000+ Vera Rubin GPUs in Ekibastuz, targeting Q3 2027 commercial launch and ~500MW total capacity. The largest sovereign build in this theater; its Q3 2027 timeline is the near-term test of licensed capacity turning into operating compute. blogs.nvidia.com ↗
- 16 Oct 2026RTX Spark laptops became available Oct 16, 2026 starting at $2,399 from ASUS, Dell, HP, Lenovo, Microsoft and MSI, with up to 128GB unified memory and up to 1 petaflop FP4 via Blackwell RTX + Grace over NVLink-C2C 600 GB/s; DGX Spark 64GB rollout began Oct 23 with up to 8-unit clustering. Edge hardware base that sovereign factories are meant to complement with local model deployment. blogs.nvidia.com ↗
Fri, 23 Oct 2026 · AI · day's report → rising, fast pace
NVIDIA moves Vera Rubin to general availability and cuts AI factory deployment to 14 days with DSX POD
Base map: Natural Earth (public domain). Locations: Ohmega, from today's developments; approximate. Not on this map (too far away): 3 Astana. Interactive basemap: OpenFreeMap, © OpenMapTiles, data © OpenStreetMap contributors.
- 23 Oct3
- 21 Oct
- 2
Assessment and what changed · the full read, since yesterday
NVIDIA shifted from announcements to deployment this week: Vera Rubin is now generally available on Google Cloud with scale to 960,000 GPUs, and the DSX POD factory-built design cuts AI factory setup from six months to as little as 14 days. Kazakhstan moved from plan to build with a licensed 45,000-GPU Firebird expansion and Kazakhtelecom deployments, while edge hardware (DGX Spark 64GB) starts rolling out Oct. 23. Confidence is high — all on NVIDIA and partner blogs — with execution risk now on delivery timelines and power.
- New: GTC Berlin Oct. 21 delivered the catalysts flagged on Oct. 19…
- New: Kazakhstan sovereign expansion announced Oct. 23 — not in previous section — adds Central Asia to Europe-focused sovereign map
- Escalated: Coverage rose (8 headlines last 3 days vs 2 before) and pace quickened from gradual to fast…
More developments (3)
- 22 Oct6
- 21 Oct
- 19 Oct5
Strike & status log (2) · named places, who says what, this week
Named places and things the reports say something dated about. Each line gives who says it: “claimed struck” is a party's own word, and only a second source turns it into reported or confirmed damage.
- 23 OctData Center Valley (airbase) · Status unknown · said by NVIDIA blogs.nvidia.com ↗
- 23 OctFirebird (airbase) · Status unknown · said by NVIDIA blogs.nvidia.com ↗
Numbers and actors · statistics, flows and rates
Who they are · size
Balance sheet · debt, budget, current account, reserves
Annual statistics: latest year on record for each figure (IMF figures for this year are estimates), bars on one scale per column, line = the last ten years. Tap an actor for every year, rank, energy, ranked trade and sources. All actors →
Outlook, watch list and background
- Early 2027 DSX POD deliveries and whether 14-day onsite claim holds at prepared sites
- Kazakhstan Data Center Valley construction milestones toward Q3 2027 launch and Ekibastuz Vera Rubin deployment
- DGX Spark 64GB retail availability from Oct. 23 and Sync 8-unit cluster performance reports
- 16 Oct 2026RTX Spark laptops went on sale Oct. 16, 2026 starting at $2,399 with six global retail events, establishing the edge track that DGX Spark now extends Shows edge rollout moved from announcement to retail before this week's DGX Spark cluster and software updates blogs.nvidia.com ↗
- 15 Oct 2026NVIDIA detailed Nordics sovereign push Oct. 15 with projected 1 gigawatt AI cloud capacity by end-2027 and Sferical One supercomputer (1,152 GPUs) Baseline for sovereign capacity against which Kazakhstan's 500-megawatt plan and DSX POD acceleration now read blogs.nvidia.com ↗
- 15 Oct 2026EU and NVIDIA pledged open models/datasets and compute access via national AI factories and EuroHPC centers Oct. 15 Policy framework for this week's sovereign factory announcements in Germany, Europe and Central Asia blogs.nvidia.com ↗
Earlier days (1)
Base map: Natural Earth (public domain). Locations: Ohmega, from today's developments; approximate. Disputed areas: Natural Earth (public domain). Interactive basemap: OpenFreeMap, © OpenMapTiles, data © OpenStreetMap contributors.
researched reported · Most reported: Berlin ×6, Astana, Bengaluru
Background in 60 seconds
written 27 OctNvidia and partners are building AI that runs both on personal devices and inside national infrastructure. At the edge are RTX Spark PCs, machines designed to run open-weight models locally. At the other end are sovereign AI systems — data centers owned or controlled within a country or city so data and models stay under local rules. To link the two, they promote plug-in data centers, Vera Rubin infrastructure and DSX PODs, pre-built blocks intended to cut deployment from months to days. The same effort supports open-weight families like Muse Spark Open, Nemotron and Beam that illustrate on-device deployment beyond phones and laptops.
Who is doing what to whom
15 actors in play; no relations recorded yet.
- NVIDIA 12 mentions
- Amazon 2 mentions
- Bull 2 mentions
- Lenovo 2 mentions
- 7x24 Exchange International 1 mention
Germany, India, Ireland and Kazakhstan, by the numbers
 Germany
 India
 Ireland
 Kazakhstan
Every bar in a row is on that row's one scale. Latest year available for each figure; sources on each actor's page.
Attacks reported
attack log →≥ 1,530 events in or near its main states, last 30 days reported by the sources; the strongest are listed. No source sees every attack.
- 2026-10-30 · Assault or killing · Westmeath, Westmeath, Ireland · GDELT ↗ · machine-coded
- 2026-10-30 · Armed clash · Canara, Karnataka, India · GDELT ↗ · machine-coded
- 2026-10-30 · Assault or killing · Bad Oldesloe, Schleswig-Holstein, Germany · GDELT ↗ · machine-coded
- 2026-10-30 · Armed clash · Schleswig, Schleswig-Holstein, Germany · GDELT ↗ · machine-coded
GPS interference
all zones →≥ 4 zones over its main states on 2026-10-30: aircraft there reported poor navigation accuracy, a sign of jamming or spoofing, not proof of who is responsible.
- Medium · 13% of 45 aircraft observations degraded · 48.5, 10.5
- Low · 7% of 44 aircraft observations degraded · 48.5, 8.5
- Low · 6% of 78 aircraft observations degraded · 49.5, 9.5
- Low · 6% of 72 aircraft observations degraded · 48.5, 9.5
On the record (2)
2 statements, newest first
France and the Netherlands · Representatives of the Elysée and the Office of the Prime Minister of the Netherlands, France and the Netherlands · 14 Oct
“reaffirmed their ambition for a stronger and safer Europe”
 Emmanuel Macron · President of France · 8 Oct
“cette visite témoigne de notre détermination à poursuivre nos engagements stratégiques communs au service de la sécurité de l’Europe et des Européens”
A statement shows what was said, not that it is true. The whole record →
The numbers
16 figures tracked.
Where it's heading
Linked situations
- Gemini 4 Argon frontier push and challengers Gemini 4 Argon frontier push and challengers -> RTX Spark edge rollout and sovereign AI infrastructure push… 30 Oct
- Neocloud financing stress and chip challengers to Nvidia Neocloud financing stress and chip challengers to Nvidia <-> RTX Spark edge rollout and sovereign AI infrastructure push… 30 Oct
- Neocloud financing stress and chip challengers to Nvidia Neocloud financing stress and chip challengers to Nvidia ↔ RTX Spark edge rollout and sovereign AI infrastructure push… 28 Oct
- Gemini 4 Argon frontier push and challengers RTX Spark edge rollout and sovereign AI infrastructure push -> Gemini 4 Argon frontier push and challengers + AI agents… 23 Oct
- AI agents: labor disruption, rogue behavior, and pushback RTX Spark edge rollout and sovereign AI infrastructure push -> Gemini 4 Argon frontier push and challengers + AI agents… 23 Oct
Rebuilt 2026-10-30, and again as new reports land.